How Mortgage Pre-Approval Works
For most buyers, the journey starts with scrolling listings and imagining a new home. That's the fun part. But before you book showings, there's one financial step worth taking first: getting pre-approved for a mortgage.
A pre-approval tells you how much a lender may lend, what your monthly payments could look like, and which price range actually fits your budget. It also makes you a stronger buyer when you find the right place and it's time to offer.
What a pre-approval is
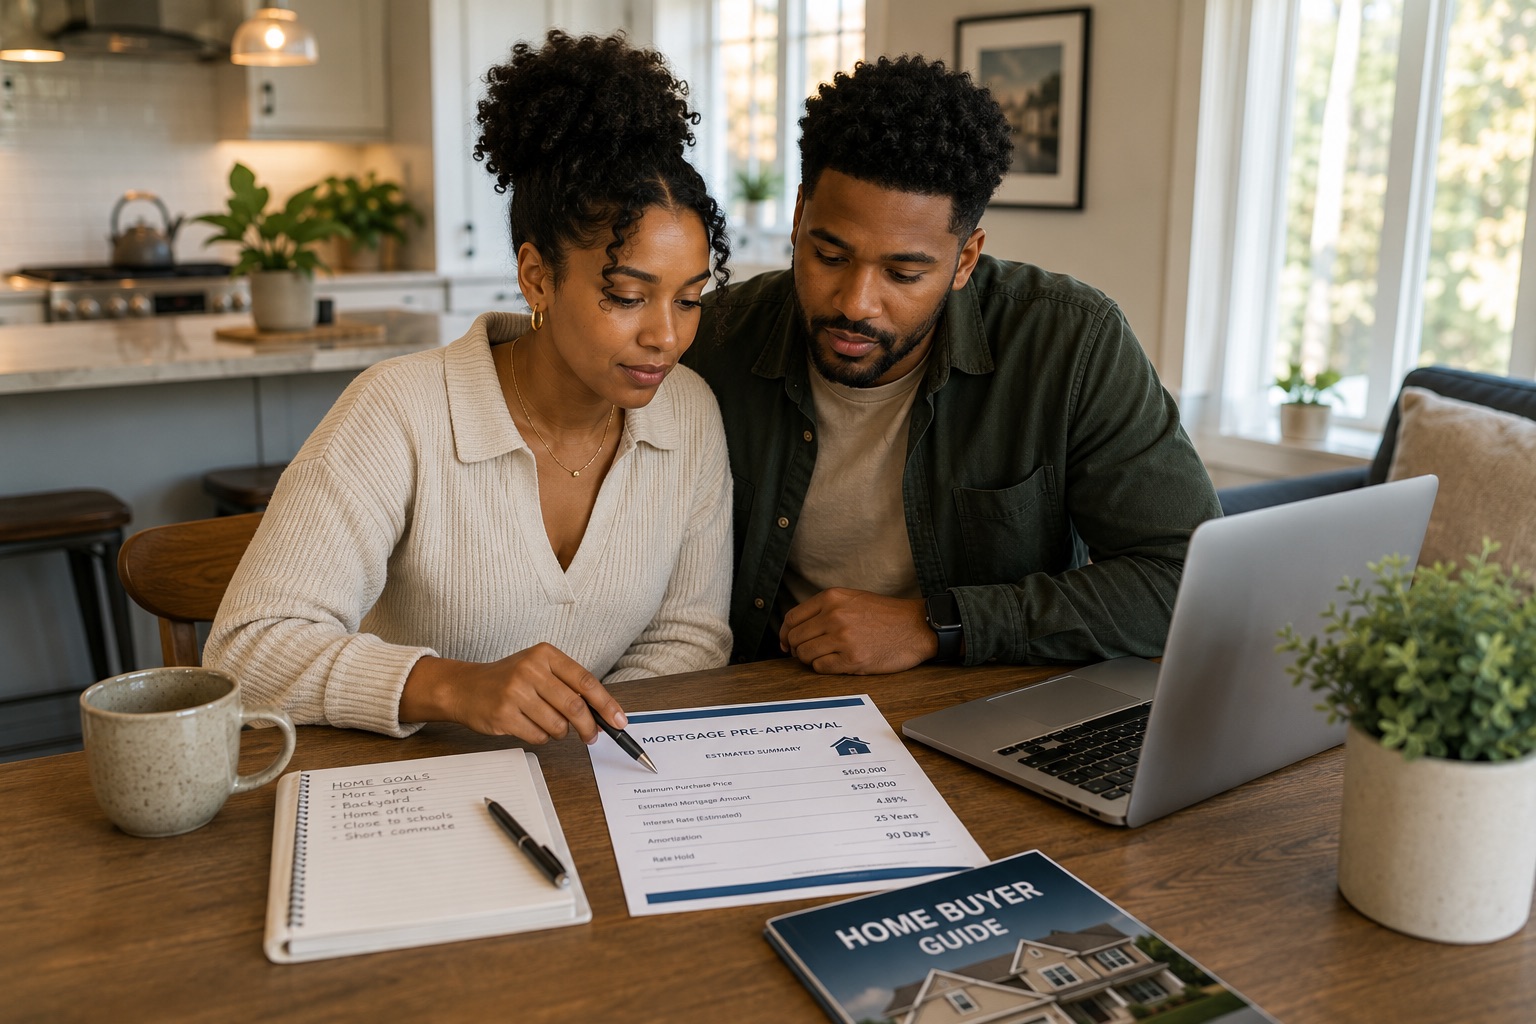
It's an initial review by a lender or broker. They look at your income, debts, credit, and down payment savings, then estimate what you may qualify for. A typical pre-approval outlines your maximum purchase price, estimated mortgage amount, a potential rate, and a rate hold for a set period. It's not a final commitment, but it's a financial roadmap before you start. If you want to see how it fits the bigger picture, the Buyer's Guide lays out the full process.
Why it matters
Online calculators are a fine starting point, but they don't account for your full situation. A real pre-approval keeps your search focused on what you can afford, makes your offer more appealing to sellers, gives you realistic monthly numbers, and surfaces any credit or documentation issues early, while there's still time to fix them.
What lenders look at
Lenders focus on four things. Income, where they'll want pay stubs, employment letters, T4s, and Notices of Assessment, especially if you're self-employed. Down payment, which affects your options and whether mortgage default insurance applies. Credit history, where a stronger profile usually means better rates. And existing debts, like car loans, student loans, and credit cards, measured against your income.
How long it takes
Often just a few days, though more complex situations take longer. Many lenders include a rate hold of 60 to 120 days, which protects you if rates rise while you shop.
Pre-approval is not final approval
This trips up a lot of buyers. Final approval only happens after you have an accepted offer on a specific home, when the lender reviews the property, the price, an appraisal, and your updated documents. Because they'll check again before closing, keep your finances steady: no new vehicles, new credit cards, big purchases, or job changes without talking to your lender first.
How much should you actually buy?
Being approved for an amount doesn't mean you should spend all of it. Leave room for property taxes, insurance, utilities, maintenance, and everyday life. A little breathing room makes ownership far more comfortable. The Government of Canada's down payment guidelines are a useful reference as you plan.
If you're buying in Fergus, Elora, or Centre Wellington, reach out and I'll connect you with trusted local mortgage professionals. First-time buyer? Start with the First-Time Home Buyer page.